Manheim’s US wholesale index fell to 206.2 in early September
The preliminary adjusted used-vehicle index was down 1% from August and 0.4% year over year. Cox reported an increase in wholesale days’ supply by September 15.
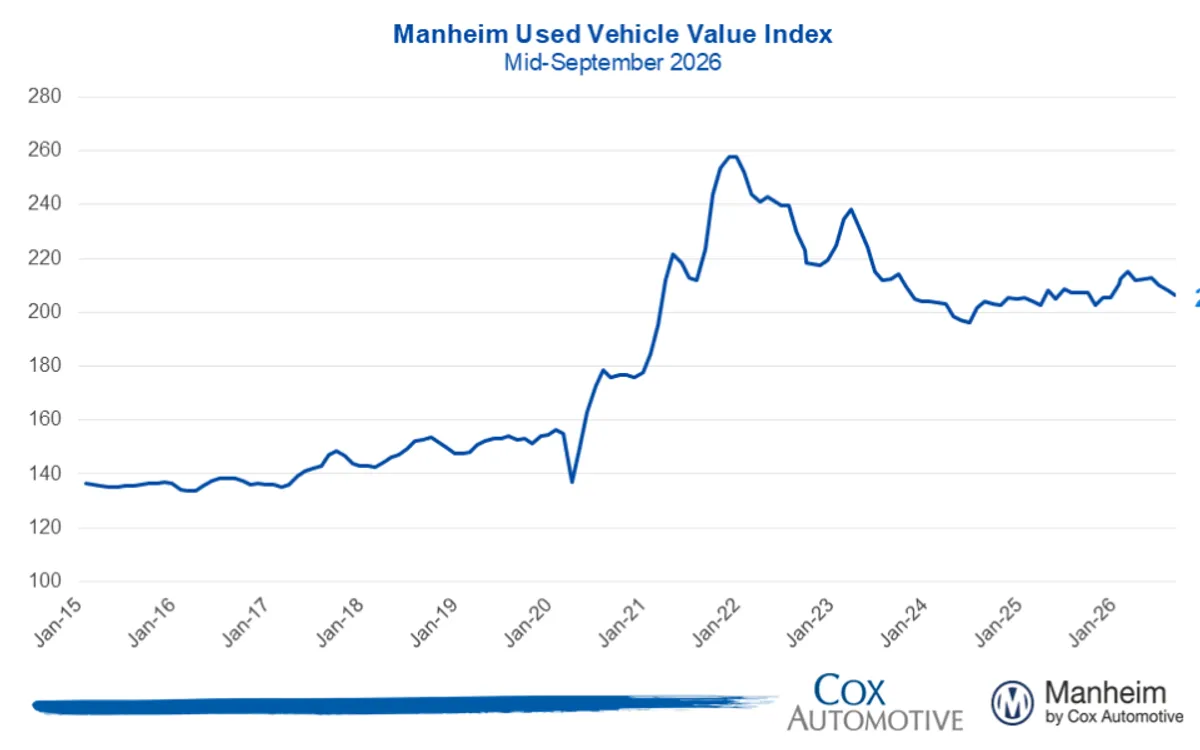
Cox Automotive said on September 18 that the adjusted Manheim Used Vehicle Value Index had fallen to 206.2 over the first 15 days of September. The U.S. wholesale benchmark was 1% lower than in August and 0.4% below September 2025. Unadjusted prices fell 1.1% on both comparisons. Cox said the preliminary reading put the year-over-year comparison into negative territory for the first time in 2026.
The index accounts for vehicle mix, mileage and seasonality. Cox’s previous full-month report had put it at 208.2 in August, up 0.4% year over year and down 0.9% from July. The preliminary September report showed a further decline from that August level. Cox put the typical unadjusted price fall for the whole of September at 0.3%, while the raw decline had already reached 1.1% in the opening half of the latest month.
Cox’s electric used-vehicle measure was 2.3% higher than a year earlier, but it fell 1.3% from August. Non-EV values fell 1.3% year over year and 1.4% from August. The last two comparisons use Cox’s powertrain indexes, which can move differently from a simple average of the wholesale market. Cox said compact cars and EVs were the only major groups with values above year-ago levels at midmonth. The report singled out midsize cars, pickups and SUVs among the groups whose declines outweighed the strength elsewhere. Cox also observed improving availability of electric used vehicles.
The auction conversion rate was 55.8% in the first half of September, down 1.4 percentage points from a year earlier. Cox’s separate price series for vehicles around three years old fell 0.8% from the beginning of the month. Wholesale supply reached 27.8 days on September 15, up from 27.2 at the end of August on the basis in the midmonth report and about 2.4 days above the year-earlier level. Lower conversion and more days of supply provide detail about vehicle sales alongside the lower prices.
Dealers assessing bids from the September report can distinguish the lower preliminary index from the categories still showing gains against the previous year. The comparison for used EVs suggests a different price environment for that part of the market. The report covers half a month, with fewer underlying auction days than a final release. The final September reading will show whether the moves continued through the remaining auctions.