EAFO October 2026: BEVs take 32.8% in 13 EU markets, charging points up 16.7%
Preliminary EAFO data show BEV registrations in 13 reporting EU Member States at 259,726 in October 2026, a 64.0% year-on-year rise and a 32.8% share, while EU27 public charging points reached 1,200,802, up 16.7% on October 2025.
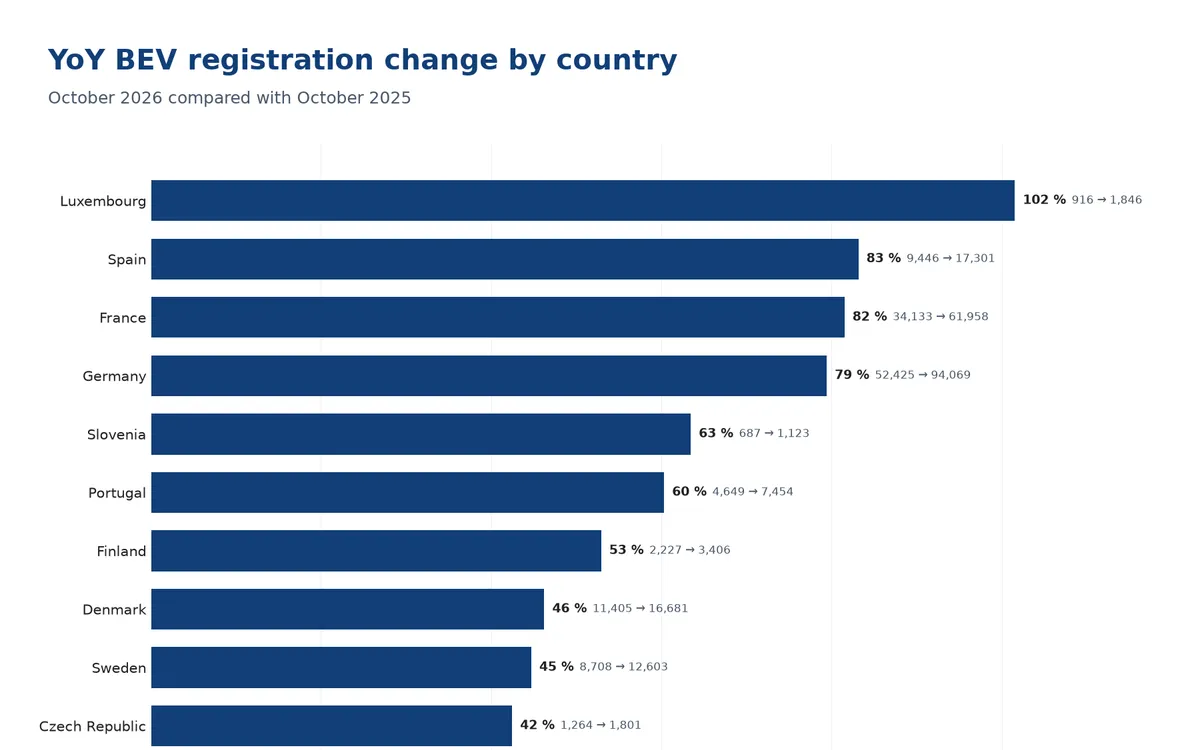
The European Alternative Fuels Observatory published preliminary October 2026 data on 2 November covering 13 EU Member States, where battery-electric registrations reached 259,726, or 32.8% of new car and van registrations. The observatory's graphic puts the year-on-year increase at 64.0%, from 158,365 in October 2025. It also reported 1,200,802 publicly accessible EU27 charging points, 16.7% more than a year earlier.
The 13 markets updated through October are Luxembourg, Spain, France, Germany, Slovenia, Portugal, Finland, Denmark, Sweden, the Czech Republic, the Netherlands, Belgium and Italy. Every other Member State is updated only through September, so the 32.8% share and the 64.0% growth describe those 13 markets, not the EU27. The charging total is a separate EU27 figure, so the two should not be combined into a single EU27 market-share claim.
Growth ranked by relative change differs from growth ranked by volume. Luxembourg posted the steepest rise, 101.5%, as registrations doubled from 916 to 1,846. Spain followed at 83.2%, France at 81.5% and Germany at 79.4%. Germany held the largest absolute volume with 94,069 units. A small base inflates the percentage, so ranking by rate and ranking by added units produce different leaders and different reads on where the incremental volume sits.
The status is preliminary and the reference periods differ by dataset. Registration counts cover September or October 2026, market-share data cover January to October 2026, and charging infrastructure covers October 2026. The next update, due 15 December, will add October and November registrations, November charging points and the January to November share series. Counts compared with the same month a year earlier are valid; cumulative-share comparisons should be made only against the same January to October span.
Charging scope is narrower than the vehicle figures. The 1,200,802-point total counts publicly accessible EU27 infrastructure; its 16.7% growth measures one month against October 2025 and says nothing about power output, connector mix, uptime or distribution across the 13 high-volume BEV markets. The BEV percentage covers new M1 car and N1 van registrations, so it is not a fleet-share measure. EAFO publishes monthly registration graphs and an FAQ for the latest single month in each country.
The practical distinction for analysts is between absolute and relative movement and between the two market boundaries. The 13-country BEV total can be compared with its own October 2025 baseline of 158,365. The EU27 charging figure cannot be mapped onto that 13-country denominator. Treating 32.8% as an EU27 share, or the +64.0% and +16.7% as a single trend, would misstate both the geographic reach and the reference period.